Refinancing a luxury car only helps when the new loan costs less than the old one after fees, not when the monthly payment merely looks smaller. A longer term can cut the payment and raise the total you pay, and on a car that depreciates quickly that can leave you owing more than the car is worth. These are general luxury car financing tips. They are not a loan offer, a rate quote, or financial advice for your file.
Refinancing is a tool, not a reset button
Look at a refinance when something real changed.
- Your credit is stronger than it was at purchase, so a bank or credit union may price you better than the original captive lender.
- Market rates fell enough to beat your current APR after the new lender’s fees.
- You want to remove a co-signer, or you are rolling out of a temporary promo rate that is about to jump.
Skip it when you are underwater and the only “deal” is a longer term that hides the balance. Also skip it if the current loan has a prepayment penalty larger than the interest you would save.
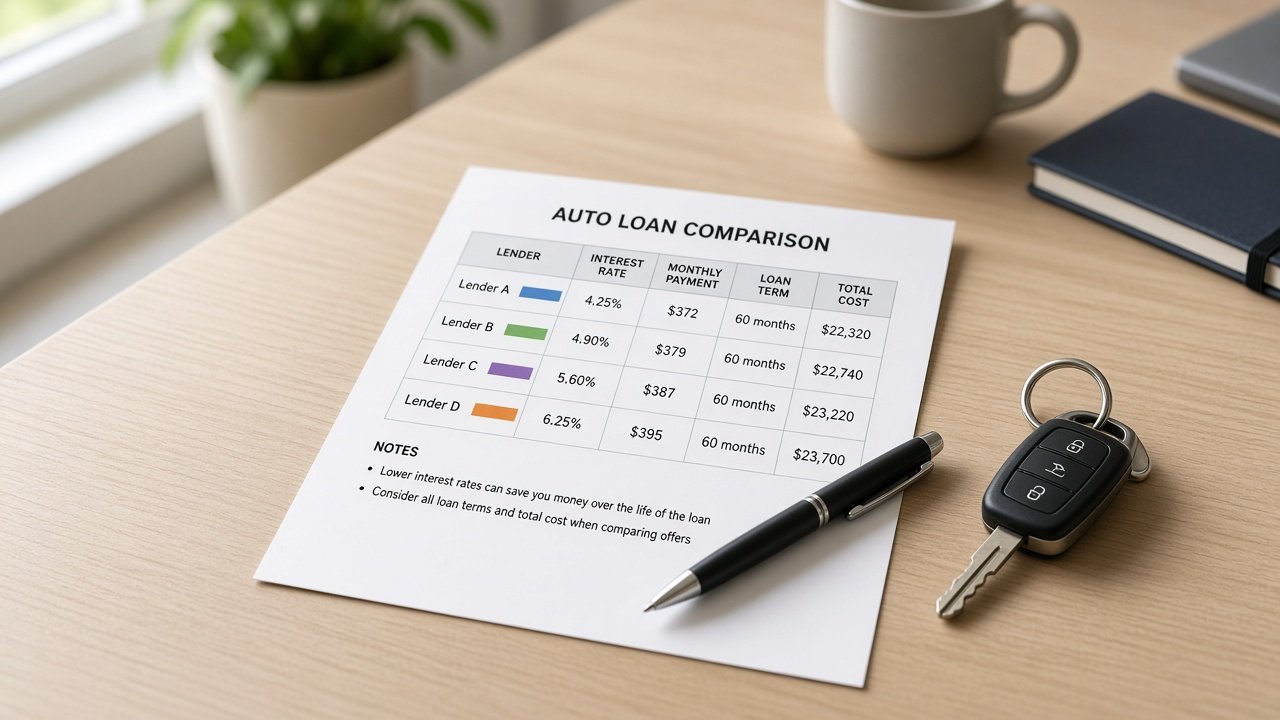
Compare the loan, not the monthly number
Ask each lender for the same facts in writing.
- APR — the rate including finance charges, not a “rate as low as” advertisement.
- Term — months remaining, not a fresh 84-month clock unless you mean to take one.
- Fees — origination, title, and any penalty to close the old loan.
- Total of payments — what you will pay from today until the end, next to the same total on the current loan.
- Payoff quote — good through a specific date. Luxury-car balances are large enough that a sloppy payoff creates a shortfall.
A lower payment with a longer term can be the wrong bargain. Run the total. If you only needed cash flow for a few months, a longer loan is an expensive way to buy those months.
Expensive cars are harder to finance than the ads suggest
- Lenders often want a larger down payment and may cap how much they will advance on a exotic or a high-mileage luxury car.
- Depreciation in the first years can outrun a small down payment. Gap coverage is worth pricing. It is not a reason to borrow more than the car is worth for add-on products you do not want.
- A balloon payment feels cheap monthly and comes due as a lump. Know where that lump will come from before you sign.
- Add-on products sold with the original loan — etched glass, prepaid maintenance you will not use, a protection package — may still be in the balance you are refinancing. Ask if any of them can be cancelled for a refund before you roll them into a new note.
Read these lines before you sign
- Prepayment penalty on the old loan and on the new one.
- Whether the rate is fixed. A variable rate on a six-figure balance is a different product.
- Compulsory insurance or a required tracking device. Walk if the explanation is vague.
- The exact vehicle and VIN on the contract. Refinancing the wrong car, or a car with a branded title the lender did not know about, becomes your problem.
We do not make loans, arrange credit, or sell vehicles. If you are buying in Orlando, the dealer’s finance office is one quote. A bank or credit union is another. Keep both.
A practical sequence
- Get the current payoff and the remaining term from the lender who holds the loan.
- Check your credit report for errors before anyone pulls a second score.
- Collect two or three written offers on the same day, same term if you can.
- Subtract fees and any prepayment penalty from the interest you expect to save.
- Only then decide. If the savings are small, staying put is a valid result.
After the car is yours, exterior parts are a separate purchase. We confirm the model and bumper, then ship aftermarket parts from China by express and quote transit time before payment. That invoice should not be quietly folded into a car loan unless you have already decided the interest is worth it. Start at the contact form.
FAQ
Is a lower monthly payment always a better refinance?
No. Stretching the term lowers the payment and can increase the total interest, and it can keep you upside down for longer.
Should I refinance as soon as rates drop a little?
Only if the new APR, the fees, and any penalty still leave you ahead on the total you will pay. A small rate change on a short remaining term often does not.
Can you finance a body kit?
We do not offer financing. We invoice the parts after the specification is confirmed. How you pay is between you and your own lender.